
Industrial real estate in the gap between institutional capital and local buyers
Flywheel acquires warehouses and manufacturing facilities below replacement cost in Columbus, Ohio and Greensboro, North Carolina
Flywheel acquires mid-size industrial buildings that are below the check size most institutional funds pursue and too complicated or capital-intensive for local investors and owner-users to take on: a vacant building that needs work, a lease rolling in eighteen months, a tenant whose credit takes real work to understand, extra land no one has priced. We buy below replacement cost, but we win these deals on underwriting and structure, not just price.
Where we invest
OUR APPROACH
01
We underwrite the business, not just the building
Whether a building is leased or vacant, its value depends on the companies that will occupy it. Flywheel’s principal spent the first decade of his career underwriting and investing in industrial companies, first in investment banking and then in private equity. We apply that lens to the credit of in-place tenants and to the demand from the businesses we expect to lease a vacant building.
We solve for the seller
02
Seller financing, excess-land carve-outs, sale-leasebacks, and recapitalizations let us create basis through structure. Our first acquisition returned roughly half its equity within nine months by extracting a land parcel out of the lease and selling surplus land.
03
We plan the exit from day one
The majority of our buildings are underwritten to lease up and sell stabilized to investors who pay for income. In markets with deep owner-user demand, like Columbus, a sale to a business that wants to own its building gives us another, and sometimes elevated exit option.
CASE STUDY
Columbus Industrial
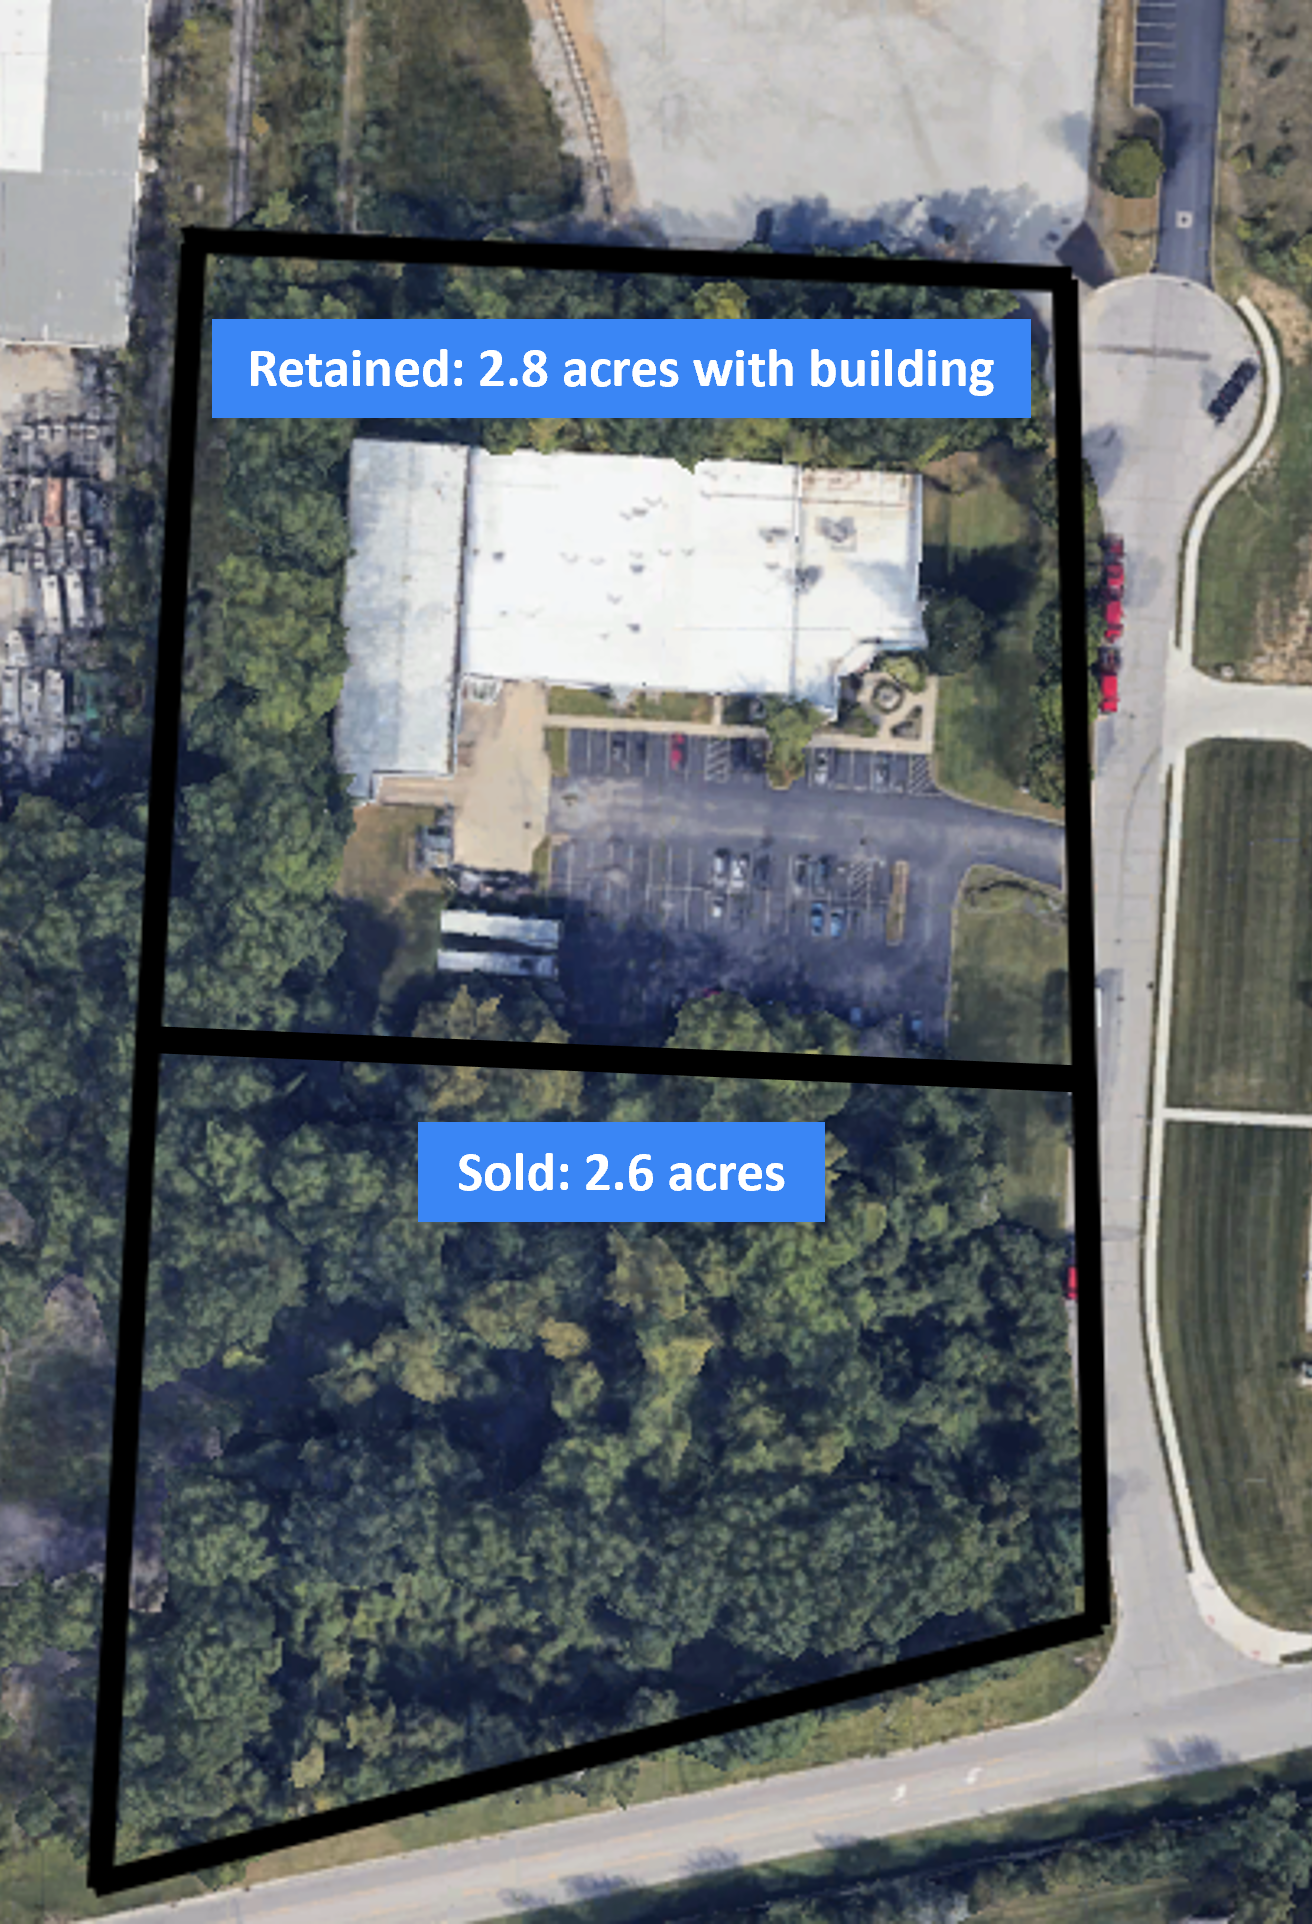
The opportunity. An off-market industrial building in Blacklick, within the Columbus airport submarket. The tenant’s single lease covered two separate parcels: the building on 2.8 acres and an adjacent 2.6-acre parcel beyond what the operation required or utilized.
What we did. We underwrote the building and the land as separate assets, then negotiated with the tenant to release the excess parcel from the lease.
The result. We sold the 2.6-acre parcel within nine months of closing, returning 50% of invested equity while retaining the leased building and its income.
July 2025
Acquired
Building (approx.)
30,000 SF
5.4 acres
Site
50%
Equity returned in 9 months
As covered by Small Bay List and IOS List
INVESTMENT CRITERIA
What we buy
Representative criteria. We evaluate every opportunity on its merits.
Single- and multi-tenant warehouse and manufacturing
Typically 20,000 to 100,000 SF
Functional clear heights, dock and drive-in access
Yard or excess land a plus
Property
Vacancy or near-term lease rollover
Short lease terms with tenant renewal options
Sale-leasebacks with owner-operators
Deferred capital needs
Excess land, carve-outs, recapitalizations
Situation
$2M to $10M purchase price
0 to 100% occupancy
Off-market and marketed opportunities
Deal Profile
Markets
Columbus, Ohio
Greensboro and the Piedmont Triad, North Carolina